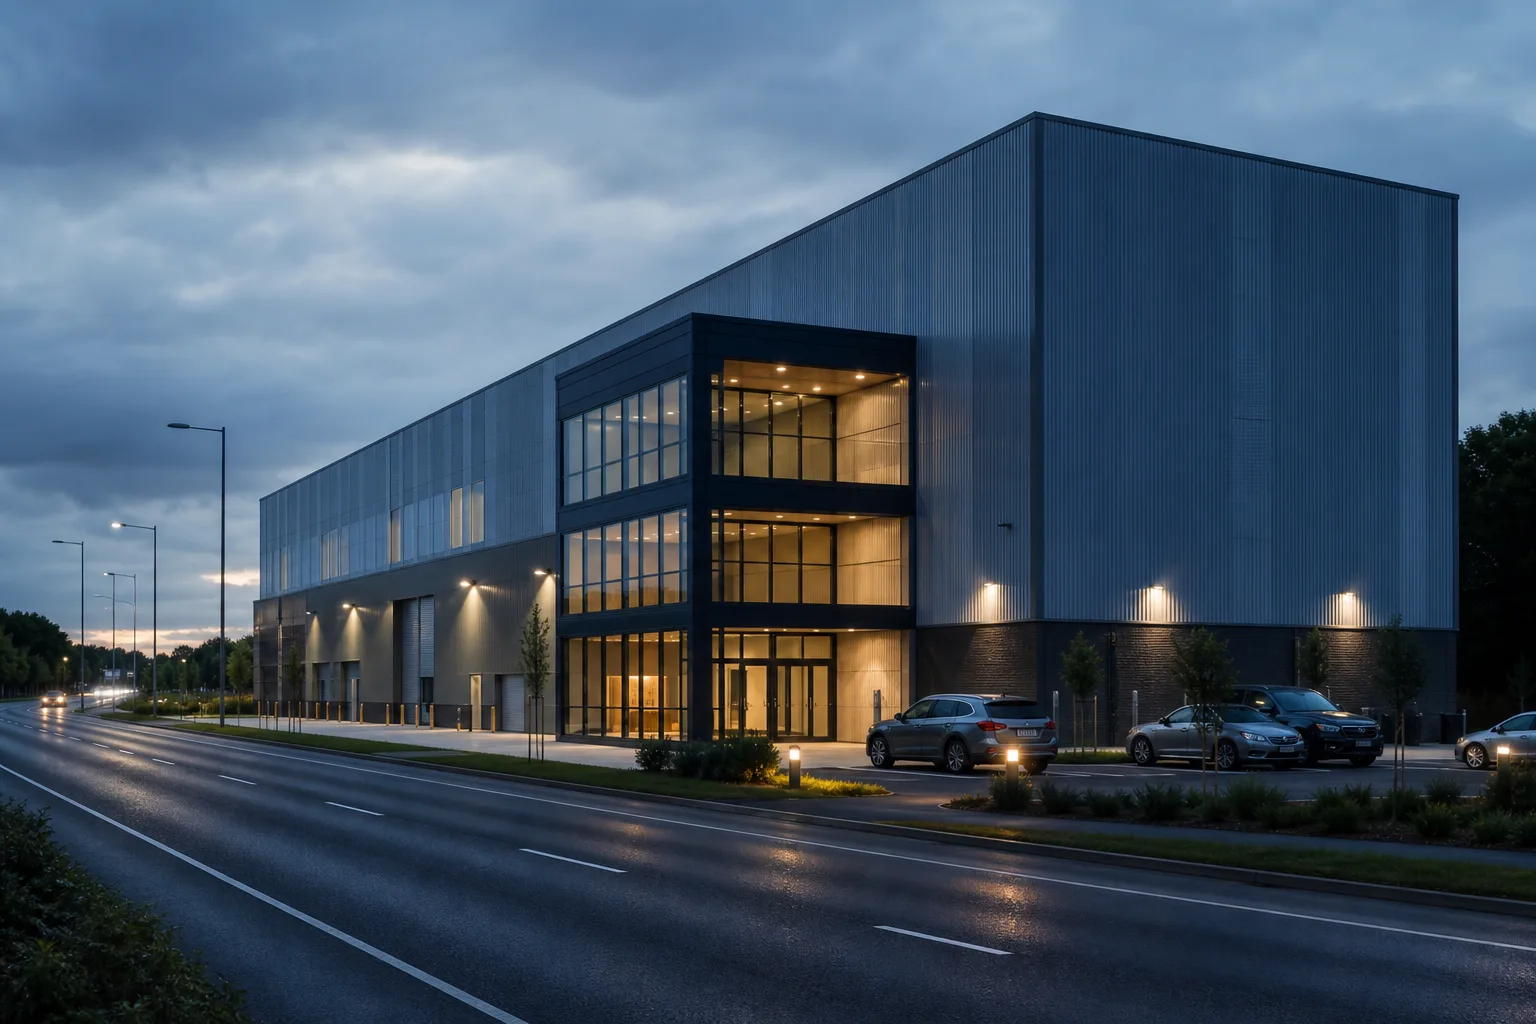
Industrial property acquisition finance
We arrange funding for the purchase of industrial investments across the UK, from single let units to multi-let estates and open storage yards.
How do you finance an industrial property purchase?
Industrial property finance is debt raised to buy income-producing industrial real estate: a single let unit, a terrace of workshops, a multi-let estate or an open storage yard. The standard route is a commercial investment mortgage sized on the rental income, with the lender testing interest cover against the net rent and lending up to around 65 to 70 percent loan to value over terms of 5 to 25 years. Where the purchase needs speed, or the asset is vacant or part-let on day one, a bridging loan completes the acquisition first and the term debt follows once the income is in place. We are an arranger and introducer, not a lender, and we build the right structure for each purchase across banks, specialist lenders and debt funds.
Light industrial has become one of the most sought-after investment sectors in the UK because the occupier base is broad, units re-let quickly and rents have grown ahead of most other commercial property. Lenders like it for the same reasons, but their appetite varies sharply by asset type: a unit let to a national trade brand on a long lease is bankable almost anywhere, while a part-let estate with short leases or an open storage yard needs more careful placement. Loans run from around 150,000 pounds to 50 million pounds and beyond, with interest rates from around 6 percent and arrangement fees of typically 1 to 2 percent. We compare the realistic terms across the market, sense-check the price you are paying against the debt it will support, and run the case through valuation and legals to drawdown.
Key features
- Funds the purchase of single units, terraces, multi-let estates and open storage yards
- Sized on net rental income, interest cover and loan to value against the investment valuation
- Term mortgages for stabilised income, with bridging available for vacant or part-let assets
- We compare rate, leverage and structure across banks, specialist lenders and debt funds
Indicative terms
- Loan size£150k to £50m+
- Loan to valueUp to 65 to 70% (investment)
- Term5 to 25 years
- RateFrom around 6% (asset dependent)
- StructureSingle unit, estate or portfolio
- Arrangement feeTypically 1 to 2%
Indicative only. Terms vary by lender, scheme and borrower and are not an offer of finance.
Who it suits
- Investors buying single let industrial units or terraces as long-term income
- Buyers acquiring multi-let estates with reversion or asset management angles
- Investors funding open storage yards and industrial land with specialist lenders
Useful calculators
Related guides
Discuss industrial property acquisition finance
A view on fundability within one working day.
What types of finance can fund an industrial acquisition?
The core instrument is the commercial investment mortgage, long-term debt secured on the property and serviced from its rent. Around it sit three complements. Bridging finance buys speed or carries an asset that does not yet qualify for term debt, for example a vacant unit being let up after purchase. Mezzanine finance sits behind the senior loan in the capital stack and lifts total leverage where the deposit available is thin, at a higher price. And for buyers funding works, refurbishment facilities advance against the cost of upgrading units, with ground-up schemes sitting with development lenders, a market our sister site Construction Capital covers.
Choosing between them is a question of income and timing. A fully let estate with a settled rent roll goes straight to a term mortgage, the cheapest money available. A tired estate bought for its reversion might use a bridge for twelve months while leases are re-geared and units refurbished, then refinance onto term debt against the improved income. We map the route before you exchange, because the wrong opening structure is expensive to unwind and the right one is often the difference between winning and losing the deal.
How much deposit is needed for an industrial property?
Plan for a deposit of around 30 to 35 percent of the purchase price on a standard investment acquisition, the counterpart of the 65 to 70 percent loan to value most lenders will advance against industrial property. On top of the deposit sit stamp duty land tax, valuation and legal costs and the arrangement fee, which together add several percent more. Assets with weaker income, short leases, heavy vacancy or unusual characteristics such as open storage land attract lower leverage, so the deposit requirement rises.
The deposit does not have to be idle cash. Equity in other property can be released by refinancing, and where you already hold industrial assets, a portfolio facility can cross-collateralise them so the next acquisition needs less cash down. Joint venture equity and mezzanine can also fill the gap between the senior loan and the price, each with a cost and a claim on the deal. Lenders will ask where the deposit comes from and some discount fully borrowed equity, so the stack has to be built openly. We structure it and evidence it as part of the application.
How do lenders underwrite an industrial investment?
The lender underwrites the income first. It tests interest cover, whether the net rent covers the interest payments with a margin, and reads the rent passing against the estimated rental value to see whether the income is reversionary or over-rented. It weighs the tenant covenant, a national trade counter operator against a local SME, the unexpired lease terms and breaks, and on a multi-let estate the weighted average unexpired term and the spread of the rent roll. Granular income from many small tenants diversifies risk, and because light industrial leases are short, rents re-gear to market quickly, which lenders increasingly give credit for.
It then underwrites the bricks. Eaves height, yard depth, loading, power and access decide the depth of the re-letting market; the EPC rating and MEES trajectory decide whether the units can keep being let as standards tighten; and the use class, B2, B8 or E(g)(iii), frames what occupiers the planning permits. Finally it underwrites the buyer: track record, other assets and the plan for the estate. We package all three layers the way credit committees want to see them, which is consistently worth more than any single point of rate negotiation.
What does it cost to buy an industrial unit or estate?
Beyond the price itself, budget for stamp duty land tax at commercial rates, the lender's valuation fee, building surveys on older stock, legal costs for both sides, and the arrangement fee of typically 1 to 2 percent of the loan. On a multi-let estate add the cost of reading every lease, because the tenancy schedule is the income you are buying. Together these costs commonly add 5 to 7 percent to the cash needed on top of the deposit.
The running costs matter to the lender as well as to you. Multi-let estates carry management: service charge administration, re-lettings, repairs and the occasional void, all of which sit between gross rent and the net income that services the debt. A single unit let on full repairing and insuring terms is the opposite, minimal management but concentrated risk in one tenant. We model the net income honestly for each asset type, because a loan sized on gross rent and serviced from net rent is how borrowers get into trouble.
Should you buy a single unit, an estate or a yard?
A single let unit is the simplest entry: one lease, one tenant, modest management and clean debt. Its weakness is concentration, when the tenant leaves the income is zero until the unit re-lets. A multi-let estate spreads that risk across many tenants and offers more ways to add value, re-gearing leases, capturing reversion, refurbishing units, but it is management-intensive and lenders look hard at the letting history and the weighted average lease term. Open storage yards, land let for vehicle parking, plant or containers, have become a recognised investment class with strong rental growth, though fewer lenders fund them and leverage is usually lower.
The debt should follow the asset, not the other way round. Single units suit straightforward term mortgages from the widest lender pool. Estates suit lenders comfortable with granular rent rolls, and reward borrowers who can evidence hands-on management. Yards need the specialist funders who lend against income from land without buildings. We know which lenders lean into each format and place the acquisition accordingly, rather than shopping it blind across desks that were never going to bite.
Worked example: buying a multi-let industrial estate
Take an investor buying a nine-unit multi-let industrial estate for 3.2 million pounds. The estate is fully let to a mix of trade, storage and light manufacturing tenants producing a net rent of 272,000 pounds a year, a net initial yield of 8.5 percent, with a weighted average unexpired lease term of just over four years. The lender offers 65 percent loan to value, an advance of 2.08 million pounds, with the investor funding 1.12 million pounds of deposit plus stamp duty and costs.
On an indicative interest rate of 6.5 percent, interest only over a 10 year term, the interest cost is around 135,000 pounds a year, so the net rent covers the payments roughly twice over, well inside the lender's interest cover test even after an allowance for voids and management. Several leases sit below the estate's estimated rental value, so the plan is to capture the reversion at renewals and refinance against the higher rent roll in year three.
This is illustrative only. The actual advance, interest rate and structure depend on the rent roll, the tenancy schedule, the buildings and the borrower, and any figures here are not an offer of finance.
Illustrative worked example only. Figures vary by lender, asset and borrower and are not an offer of finance.
Industrial property acquisition finance: common questions
Can I get a 100% commercial mortgage?
Not against the property alone. Lenders cap industrial investment loans at around 65 to 70 percent loan to value, so the balance must come from somewhere. Borrowers reach effective full funding by adding additional security over other property, releasing equity elsewhere, or layering mezzanine finance behind the senior loan. Each route has a cost, and we model whether the deal still works once it is counted.
What are the three types of finance?
The classic split is debt, equity and mezzanine. Debt is borrowed money secured on the asset, the commercial mortgage or bridging loan. Equity is the buyer's own capital, the deposit. Mezzanine sits between the two, ranking behind the senior debt but ahead of equity, lifting total leverage at a higher price. Most industrial acquisitions use senior debt plus equity, with mezzanine added selectively.
Should I buy industrial property through a limited company?
Most investors now buy through a limited company or SPV for tax and structuring reasons, and lenders are entirely comfortable with it, typically taking a charge over the property, a debenture over the company and personal guarantees from the directors. Whether a company is right for you is a tax question for your accountant; we arrange the finance for either route.
How long does an industrial property purchase take to fund?
A term mortgage typically takes 8 to 12 weeks from application to drawdown, covering credit approval, valuation and legals. Where the seller demands faster completion, or the asset is being bought at auction, a bridging loan can complete in 2 to 4 weeks with the mortgage following as the exit. We plan the timetable around the deal, not the other way round.
Is industrial property finance regulated?
Lending to companies and investors buying industrial property for business purposes is normally unregulated commercial lending. Where a transaction involves an individual and falls within the regulated mortgage definition, for example security connected to the borrower's home, we refer it to an appropriately authorised firm.
Discuss industrial property acquisition finance
Send us your scheme and we will come back with a view on fundability and likely terms within one working day.